Personal insurance
Personal Accident Insurance
Financial support if an accident causes death or disability — the gap that health insurance alone doesn't fill.
Who is it for?
Is personal accident cover right for you?
- Daily commuters and two-wheeler riders
- Self-employed people whose income stops if they can't work
- Professionals in field or travel-heavy roles
- Families who want protection alongside health and life cover
What does it help protect?
The risk, in plain English
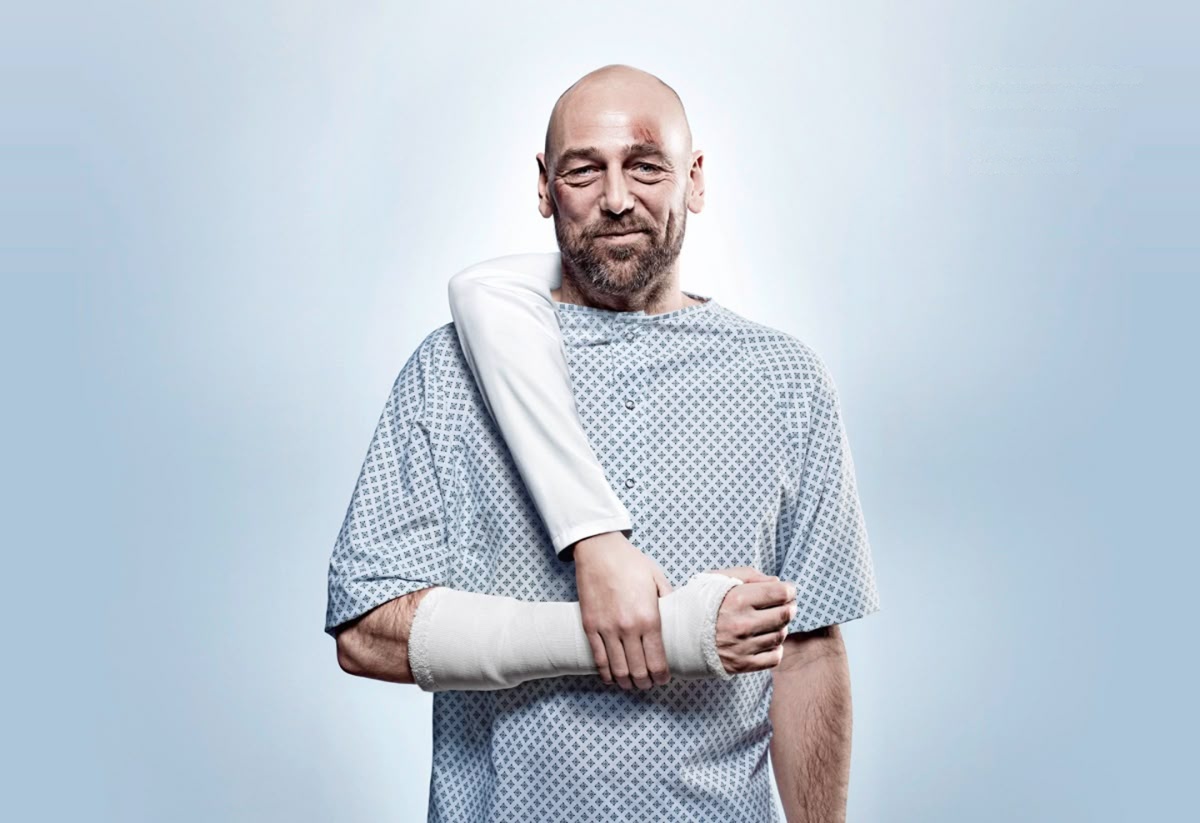
Health insurance pays hospital bills, but an accident can also stop your income for months or permanently. Personal accident insurance pays defined benefits for accidental death and disability, regardless of medical bills.
Key cover areas
What a policy typically includes
Cover differs between insurers and plans. These are the areas we walk you through — the policy wording always decides.
Accidental death
A lump sum to the nominee if death results from an accident.
Permanent total disability
A benefit if an accident leaves you permanently and totally disabled.
Permanent partial disability
A percentage of the sum insured based on a defined disability table.
Temporary total disability
A weekly benefit while you are unable to work, in plans that include it.
Additional benefits
Depending on the plan, items such as children's education benefit or accidental hospitalisation.
What to check
Read this before comparing premiums
The cheapest policy is rarely the one that serves you best at claim time. These are the terms we always check with you.
- Sum insured basis
- Insurers typically link cover to income — understand the limits that apply to you.
- Disability definitions
- How the policy defines total and partial disability and the benefit table used.
- Occupation class
- Your occupation can affect premium and acceptance.
- Exclusions
- For example, injuries under the influence of intoxicants or from hazardous activities.
How Finmirai helps
Advice before you buy. Support after you do.
As your broker, our job is to understand your need, explain options honestly and stay with you for servicing and claims.
- Listen first: we understand your family, health, assets and budget before discussing any plan.
- Explain options in plain language, including what is not covered.
- Help you compare suitable options and complete the proposal and documentation correctly.
- Remind you ahead of renewals and help with changes during the policy year.
- Guide you through the claims process and the documents the insurer will ask for.
How it works
- 1
Tell us
Share your requirement by form, call or WhatsApp.
- 2
Understand your need
We ask the questions that shape the right cover.
- 3
Compare options
We identify suitable options and explain the differences.
- 4
You choose
You decide, with clarity on cover, exclusions and cost.
- 5
Policy issued
We help with proposal, documentation and issuance.
- 6
Ongoing service
Renewals, changes and claims guidance through the year.
FAQs
Personal Accident Insurance: common questions
Isn't health insurance enough?
Health insurance pays for treatment. Personal accident cover pays fixed benefits for death or disability caused by accidents, which can replace lost income. The two work together.
Is personal accident cover expensive?
Premiums are generally modest relative to the cover, because the policy covers accidents only. The exact premium depends on the sum insured and occupation.
Does it cover illness?
No. Personal accident insurance covers bodily injury caused by accidents, not illnesses.
Can I have more than one personal accident policy?
Generally yes. Unlike indemnity policies, fixed-benefit policies may pay under each policy, subject to each policy's terms and disclosure.
Does my motor policy's PA cover protect me fully?
The compulsory owner-driver PA cover in a motor policy applies only to accidents connected with that vehicle and has a fixed limit. A standalone policy covers accidents more broadly.
Get insurance assistance
Talk to us about personal accident cover
Share a few details and an advisor will contact you. There's no obligation to buy.
Related
You may also want to consider
Health Insurance
Individual and family floater cover for hospitalisation and related medical costs.
Learn moreLife & Term Insurance
Term and life cover that protects your dependants if the unexpected happens.
Learn moreMotor Insurance
Third-party and comprehensive cover for private cars and two-wheelers, with renewal support.
Learn more